Ethical Investing
Every holding passed the screen. Is the portfolio still too concentrated?
18 October 2026 · FinAnalytic Editorial · 3 min read
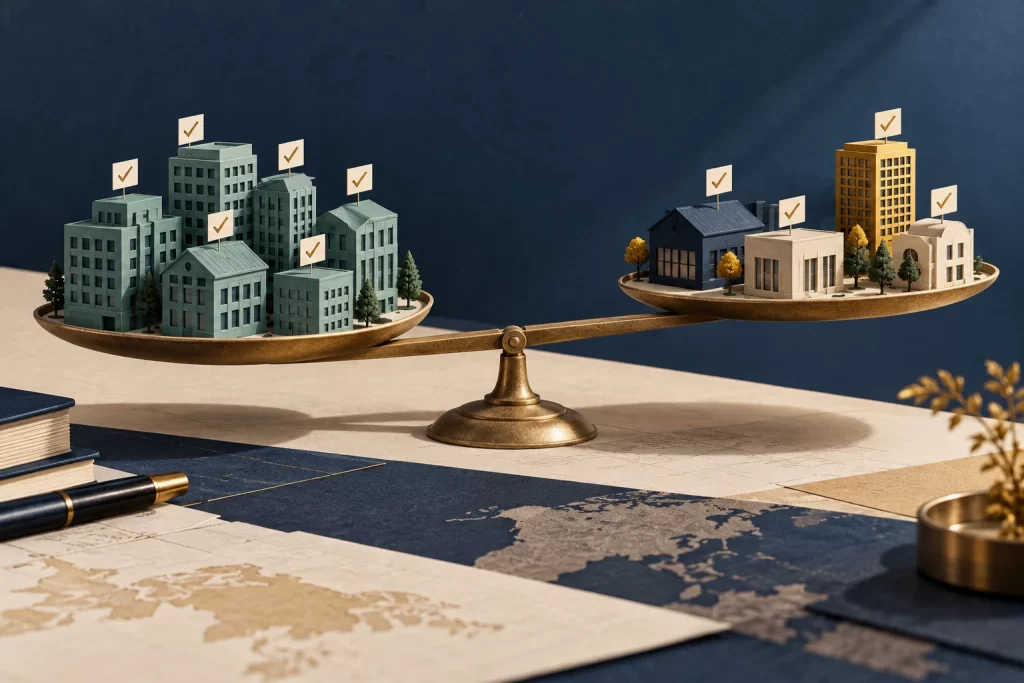
Picture an investor who has carefully checked every company in a portfolio against a chosen Shariah framework. The list looks reassuring. Then a friend asks a different question: how much of the money depends on the same industry?
Eligibility is only one part of the picture
This illustrative investor has done meaningful work. But a screen determines whether a company meets a defined set of criteria; it does not establish that any combination of eligible companies makes a balanced portfolio.
NSE Indices describes the Nifty500 Shariah as constituents of the Nifty 500 screened for Shariah compliance. Its methodology sets out business and financial screening. Because those tests filter the starting universe, the resulting exposures can differ from the parent index.
That is a reason to examine the actual holdings and weights. It is not a claim that every screened portfolio has the same sector bias.
Count the exposure, not the number of names
Suppose, purely for illustration, a ₹10 lakh equity portfolio holds ten companies. Four account for ₹6 lakh and rely heavily on a similar source of customer demand. The portfolio has ten names, but 60% of its value shares that particular exposure.
Even companies in different sectors can depend on the same conditions. A currency move, a common export market or a rise in energy costs may affect several businesses together. The useful review looks at those dependencies alongside the sector labels.
Start with a plain holdings sheet showing current value, percentage weight, sector and the main business risks. The largest positions deserve the clearest explanations.
Check overlap across products
Buying a second fund can feel like diversification. If both products hold many of the same large positions, the change may be smaller than it appears.
Combine direct shares and fund exposures where holdings information is available. Note the date of each disclosure: a fund’s published portfolio is a snapshot, and it may have changed. Where information is missing, record the gap rather than assuming the exposure is small.
SEBI’s general investor guidance discusses diversification and reviewing allocations against objectives. Applying those principles within an investor’s ethical constraints still requires attention to the investments actually available.
Keep two review questions separate
One review asks whether a holding remains eligible under the chosen framework. Another asks whether its size and risk still fit the investor’s circumstances. A company can pass the first review and deserve a smaller weight in the second.
Document which framework and adviser guide eligibility, including any income-purification process. Religious interpretation and product implementation can differ. A broad statement that an asset is “ethical” does not settle those details.
Do not fill a gap with an unsuitable product
If the permitted investment universe leaves a difficult diversification problem, make that constraint explicit. Adding an unfamiliar or illiquid product simply because it carries a suitable label can create another problem.
Discuss the choices with advisers who understand both the investment objective and the selected Shariah requirements. Check liquidity, costs, governance and the ability to bear losses.
Our investor’s next useful task is a one-page exposure review. The screening work remains valuable. Now it sits alongside a clearer view of what could cause several holdings to struggle at once.
Sources & further reading
- NSE Indices, Nifty500 Shariah index overview
- NSE Indices, Methodology Document for Nifty Shariah Indices
- SEBI Investor, Factors to Consider Before Investing
Research checked 18 October 2026. Scenarios and calculations are illustrative unless identified as reported facts.